Almost all global ocean carriers are preparing to make a tentative return to Suez Canal transits in October 2026, according to reporting from The Loadstar published October 1. The Premier Alliance, which includes some of the world’s largest container lines, is preparing to bring its Asia to North Europe services back through the Suez route this month. If the return holds, it would represent the first meaningful shift in global ocean routing since the Red Sea crisis forced vessels onto the longer Cape of Good Hope route in early 2024. For shippers, a Suez routing return does not mean the freight market normalizes overnight. It means a significant piece of the cost and capacity equation is shifting and understanding how is essential for Q4 planning.
What is actually changing
The Red Sea crisis that began in late 2023 forced carriers to reroute vessels away from the Suez Canal and around the Cape of Good Hope, adding approximately seven to ten days to Asia to Europe transit times and absorbing a significant portion of global effective container capacity in the process. That longer routing, combined with the Strait of Hormuz closure since February 2026, has been one of the structural drivers of elevated ocean freight rates throughout the year.
The return to Suez is described as tentative rather than wholesale, and the word tentative carries real weight here. Carriers are not returning because the security environment in the Red Sea has fully normalized. They are returning because the cost and schedule pressure of the longer Cape routing has become difficult to sustain at scale, and because the security risk calculation appears to have shifted enough to make the shorter route viable for some vessels and some services.
Not every carrier and not every service will return simultaneously. The Premier Alliance services confirmed for October represent a significant portion of Asia to North Europe capacity, but the broader market return will depend on how the initial sailings go and whether the security situation holds. Shippers should monitor their specific services rather than assuming the Suez return applies uniformly across all trade lanes from day one.
What it means for Asia to Europe rates
The most direct market effect of carriers returning to Suez is on Asia to Europe freight rates. The longer Cape routing added cost and absorbed capacity simultaneously. When capacity is absorbed by longer voyages, fewer vessels are available for a given number of sailings, which supports rates. When vessels return to the shorter Suez route, effective capacity increases and the per-voyage cost decreases.
The direction of that effect on rates is downward pressure. How quickly and how significantly rates move depends on how many vessels return, how quickly volumes adjust to the changed routing, and whether the additional effective capacity is absorbed by demand growth or creates genuine surplus.
For shippers on Asia to Europe trades who have been paying elevated rates driven partly by the Cape routing premium, the October return is the first meaningful potential relief from that specific cost driver since the crisis began. Whether to wait for rates to soften before booking or to lock in current rates before a new demand surge absorbs the additional capacity is the decision this development creates.
What it means for Asia to US trades
The Suez Canal return has a less direct but still meaningful implication for Asia to US trades, including the Transpacific routes that most US shippers care about most.
The vessels currently routing around the Cape of Good Hope are tying up capacity that would otherwise be available for other trades. When those vessels return to the Suez route and recover the transit time premium, some of that capacity becomes available for redeployment. That redeployment could flow into the Transpacific market as carriers optimize their networks around the changed routing.
More immediately, the Suez return affects the transshipment hubs that connect Asia to US East Coast services. Colombo, Singapore, and other major transshipment points have been under increased pressure as routing shifts have created congestion. The Loadstar reported October 2 that Colombo is becoming a transshipment hot-spot as India to US trades are heaping cost pressure onto forwarders. A partial normalization of routing through the Suez could ease some of that transshipment pressure over the coming weeks.
The congestion context this return lands into
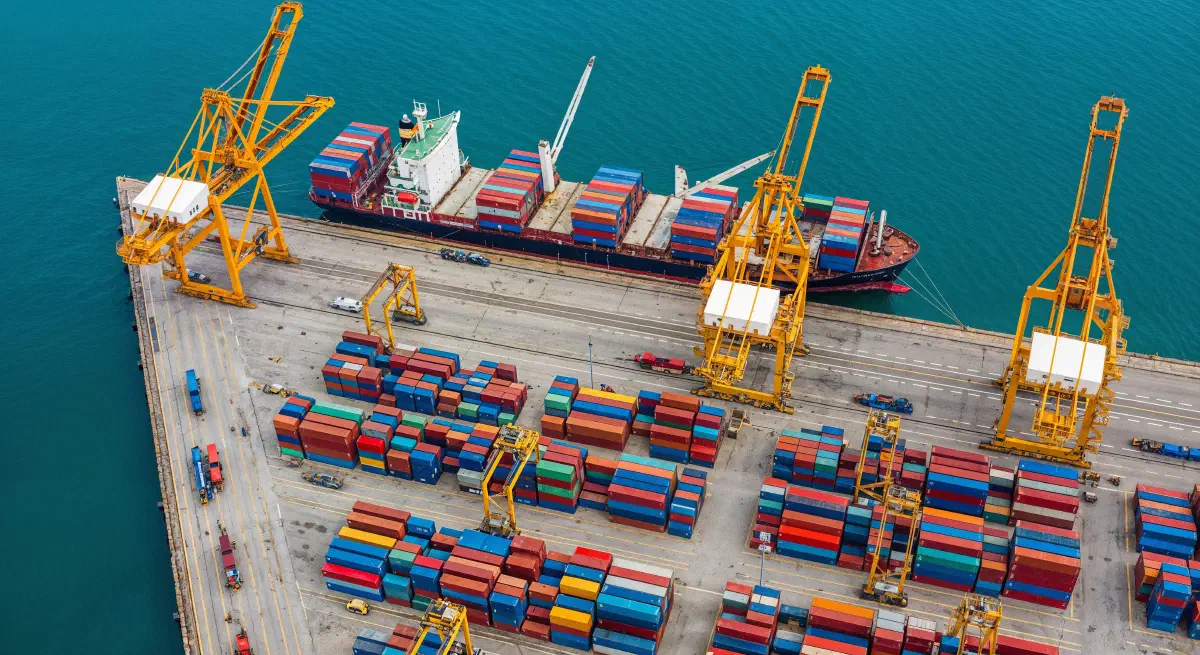
The Suez Canal return is happening into an Asian port system that is still heavily congested. Container congestion in Asia is expected to persist into 2027, with 8.5 percent of the global container fleet currently tied up in delays. That is equivalent to roughly 3 million TEUs of capacity effectively removed from the market, more than the capacity of all but four of the world’s largest carriers.
Repeated typhoon disruptions have been at the heart of the problem. Backlogs that began with Typhoon Dolphin in August and compounded with Typhoon Saudel in September have cascaded through transshipment hubs in ways that are not resolving quickly. A Suez Canal return does not fix that congestion. It changes the routing equation on top of a network that is still absorbing significant disruption-driven delays.
For shippers, this means the Suez return is a positive development for one specific cost driver, the Cape routing premium, without resolving the broader congestion and rate environment. The net effect on what shippers actually pay will depend on how quickly the routing normalisation feeds through to rate structures versus how much the persistent congestion continues to support carrier pricing.
What shippers should watch and do right now
Confirm whether your Q4 sailings are affected by the routing change.
If you have bookings on services that are returning to the Suez route in October, confirm with your freight partner whether your specific sailing is affected and whether revised transit times change your delivery estimates. A shorter transit time on a returning Suez service may allow you to adjust shipping windows for late Q4 orders.
Do not immediately assume rates will fall.
The Suez return reduces one cost driver but does not eliminate the persistent congestion, the Panama Canal restrictions, or the Strait of Hormuz closure that are the other major structural factors in the current rate environment. Rate movements on Asia to Europe trades will be the first to reflect the routing change. Transpacific rates may take longer to adjust and may adjust less sharply.
Use this development as a trigger for a Q4 routing review.
If your current Q4 ocean freight strategy was built around Cape routing assumptions, it should be reviewed against the October Suez return. Transit times, port call sequences, and transshipment connections all change when services move back to the Suez route. A routing review with your logistics partner now catches any adjustments needed before your Q4 shipments are in transit.
At HighQ Logistics, we monitor ocean routing developments alongside the domestic freight markets we manage daily, so that when a structural change like the Suez return affects your transit times and cost assumptions, you know before your freight does. If you want to understand how the October carrier routing changes affect your Q4 import program, talk to the HighQ team or get a freight quote.
Almost all global ocean carriers are preparing to return to Suez Canal transits in October, ending nearly two years of Cape of Good Hope routing that added transit time and absorbed global container capacity. The return is tentative, not wholesale, and lands into an Asian port system where 8.5 percent of the global fleet is still tied up in congestion-related delays. Shippers should expect downward pressure on Asia to Europe rates as the routing premium unwinds, monitor how the return affects their specific services and transit estimates, and review Q4 routing assumptions against the changed network configuration rather than waiting for invoices to reflect the change.
Frequently Asked Questions
Why are ocean carriers returning to the Suez Canal in October 2026?
Almost all global ocean carriers are preparing to make a tentative return to Suez Canal transits in October, according to The Loadstar reporting October 1. The return reflects a shift in the security risk calculation around Red Sea transits that makes the shorter route viable again for some services after nearly two years of routing around the Cape of Good Hope. The Premier Alliance is among the first alliances confirmed to return Asia to North Europe services to the Suez route this month.
What happened to Suez Canal routing in the first place?
Red Sea security threats beginning in late 2023 forced carriers to reroute vessels around the Cape of Good Hope rather than transiting the Red Sea and Suez Canal. The longer routing added approximately seven to ten days to Asia to Europe transit times and absorbed a significant portion of global effective container capacity, contributing to elevated freight rates throughout 2024 and 2026.
How will the Suez Canal return affect ocean freight rates?
The most direct effect is on Asia to Europe rates, where the Cape routing premium has been a specific cost driver. Returning to the shorter Suez route reduces per-voyage cost and increases effective capacity, which creates downward pressure on rates. How significantly rates move depends on how many vessels return, how quickly, and whether the additional capacity is absorbed by demand or creates surplus. The effect on Transpacific rates will be less direct and slower to materialise.
Does the Suez return mean ocean freight is normalizing?
Not entirely. The Suez return addresses one structural factor in the elevated rate environment, the Cape routing premium, without resolving the others. Container congestion in Asia is expected to persist into 2027, with 8.5 percent of the global fleet currently tied up in delays. The Panama Canal continues to operate with reduced slot availability. The Strait of Hormuz remains effectively closed to normal commercial traffic. The routing change is a positive development but not a market reset.
Should shippers wait for rates to fall before booking Q4 ocean freight?
The Suez return creates downward pressure on rates but the timeline and magnitude of any rate softening is uncertain. Persistent Asian port congestion and Panama Canal restrictions continue to support carrier pricing from the demand side. Shippers who have not yet locked in Q4 ocean freight arrangements face a genuine choice between waiting for potential rate softening and accepting the risk that congestion or demand growth absorbs any relief before it reaches their booking window.
How does the Suez return affect transit times on my shipments?
Services returning to the Suez route will have shorter transit times on Asia to Europe and Asia to Mediterranean lanes. The magnitude depends on the specific port pair and previous routing. Shippers with bookings on returning services should confirm revised transit estimates with their freight partner, as shorter transits may allow adjusted shipping windows for late Q4 orders.
What should shippers do right now in response to the Suez return?
Confirm whether your Q4 sailings are on services affected by the routing change. Review Q4 routing assumptions with your logistics partner to identify any transit time or port call sequence changes. Do not assume rates will fall immediately or significantly on Transpacific lanes, where the routing change has a less direct effect. Use the development as a trigger for a Q4 routing review rather than a reason to delay freight bookings.